E-Invoicing in Germany 2027: Requirement, Timeline, Format & Examples


Germany's B2B e-invoicing mandate is rolling out in phases under the Growth Opportunities Act (Wachstumschancengesetz). Since 1 Jan 2025, all businesses must be able to receive structured e-invoices. From 1 Jan 2027, businesses with 2026 turnover above €800,000 must issue them for domestic B2B supplies, and from 1 Jan 2028, the obligation applies to all. The BMF letter of 15 Oct 2026 confirms these dates and clarifies validation, corrections and attachments. Beyond compliance, the shift standardises invoice formats, reduces manual AP/AR work, and marks Germany's first step toward ViDA alignment by 2030.
Key Takeaways
- From 1 Jan 2027, businesses whose total 2026 turnover exceeded €800,000 must issue structured e-invoices for domestic B2B supplies. All others follow from 1 Jan 2028.
- Since 1 Jan 2025, every business in Germany, including small businesses, must be able to receive EN 16931 e-invoices. The recipient's consent is not required.
- Accepted formats include XRechnung and ZUGFeRD from version 2.0.1 (all profiles except MINIMUM and BASIC-WL). Peppol, EDI and email are permitted transmission channels.
- The BMF letter of 15 Oct 2026 confirms that a business-rule validation error does not automatically invalidate an e-invoice, and that all mandatory VAT data must sit in the structured part.
- Exemptions cover B2C sales, cross-border supplies, invoices up to €250 gross, passenger tickets, most VAT-exempt supplies and small businesses under §19 UStG (up to €25,000 prior-year and €100,000 current-year turnover).
- E-invoices must be archived in their original structured format for 8 years under §14b UStG and §147 AO.
What is e-Invoicing in Germany?
An e-invoice is an invoice issued, sent, and received in a structured electronic format that computers can read and process automatically. Unlike a PDF or paper invoice, it eliminates manual data entry, enabling faster, error-free exchange between accounting systems.
E-invoicing in Germany is exchanging invoices in a structured electronic format compliant with the EN 16931 standard, such as XRechnung or ZUGFeRD, not a normal or scanned PDF emailed to a customer. It applies to domestic B2B transactions, while B2G invoicing follows separate public-sector rules. E-invoices can be transmitted through channels such as Peppol, service provider platforms, EDI or email, enabling automated validation and posting in accounting systems. Businesses must also archive e-invoices for 8 years to remain compliant.
Germany's B2B e-invoicing mandate was introduced through the Growth Opportunities Act (Wachstumschancengesetz) and implemented through amendments to Section 14 of the German VAT Act (UStG). The BMF has since published three application letters, on 15 Oct 2024, 15 Oct 2025 and 15 Oct 2026, which update the VAT Application Decree (UStAE) and answer practical questions on formats, validation, corrections and attachments.
Germany E-Invoicing Timeline and Compliance Deadlines
Germany's e-invoicing timeline has three stages: receiving e-invoices became mandatory on 1 Jan 2025, businesses with 2026 turnover above €800,000 must issue them from 1 Jan 2027, and all businesses must issue them from 1 Jan 2028. The 1 Jan 2027 date is confirmed, and no postponement is expected.
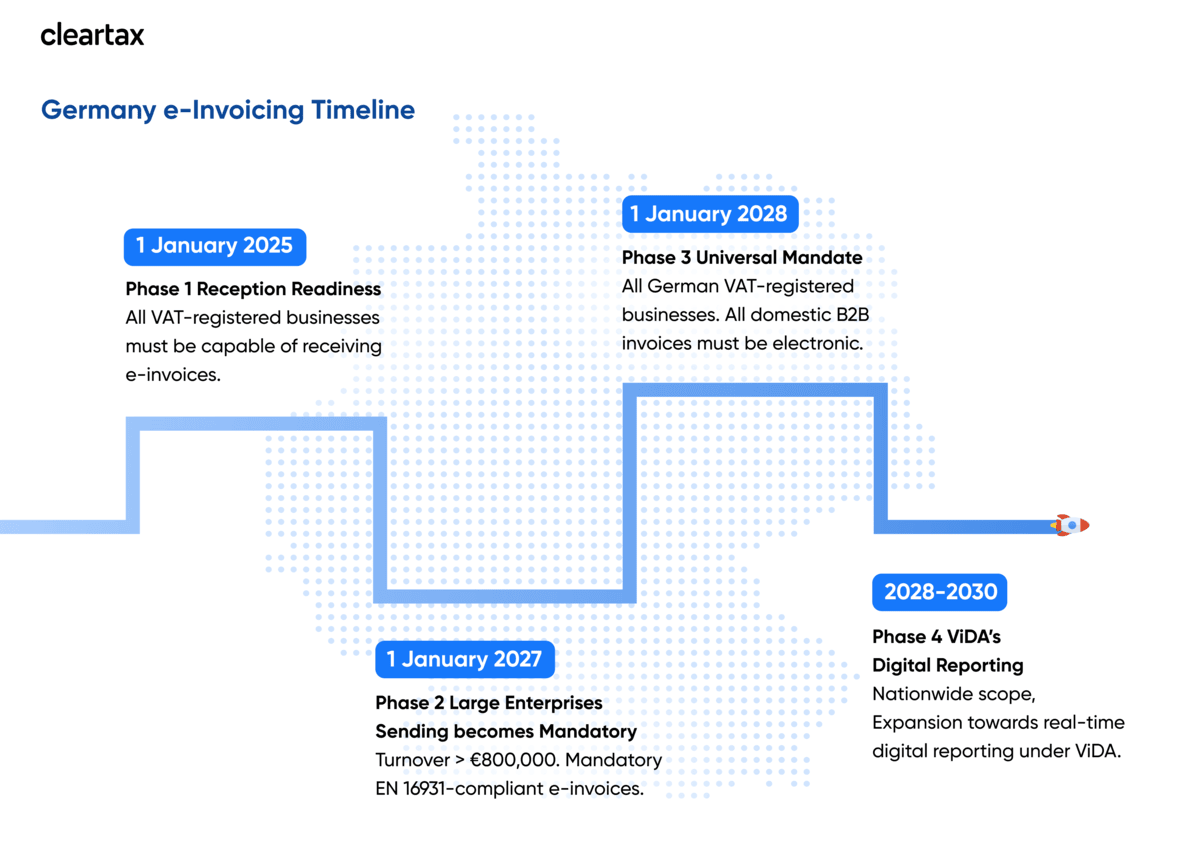
The transition rules follow the date the supply is made. Consent to a non-structured format needs no formal process and can be given implicitly, for example by paying the invoice. Receiving has applied to every business since 1 Jan 2025.
What Changed with the BMF Letter of 15 Oct 2026?
The BMF's third e-invoicing letter, published on 15 Oct 2026, keeps the 1 Jan 2027 deadline unchanged and clarifies four practical points:
- Validation errors: If a file has no format error, a business-rule error only matters for VAT when it affects mandatory VAT data.
- Structured data: All mandatory VAT information must sit in the XML. A reference to a contract alone is not enough.
- Attachments: Timesheets or contracts must be embedded in the e-invoice file, not sent separately or linked.
- Input VAT: Incomplete invoices must be completed before input VAT can be deducted, and delivery notes can't fill the gaps in an e-invoice.
How Does E-Invoicing Work in Germany?
E-Invoicing in Germany works through a structured process, from XRechnung or ZUGFeRD-compliant creation and transmission through Peppol or EDI, to receipt validation, 8-year archiving, and post-audit compliance as mentioned below:
- E-Invoice Creation (Erstellen): A business prepares the bill using ERP platforms, bookkeeping applications, or an electronic invoicing solution provider. It should also have all tax details correctly written as per VAT compliance. The document must comply with German standards such as XRechnung or ZUGFeRD.
- Transmission: The invoice is sent to trading partners via email, EDI, Peppol network, or service provider platforms. The channel may be chosen by agreement. But the invoice itself must stay structured.
- Receipt and Validation (Empfangen): The recipient's software checks format and data integrity, then posts valid e-invoices to the ERP or accounting system. No recipient consent is needed for EN 16931 e-invoices.
- Processing & Archiving: The invoice must remain preserved in its native electronic form for 8 years. It should remain genuine, intact, readable, plus accessible for audit.
- Post-Audit Compliance: Tax authorities in Germany do not receive invoices in real time. They may request invoice data during an audit, and there is no pre-clearance or live reporting obligation yet, though a VAT reporting system is planned.
- B2G E-Invoicing: For federal authorities, invoices are submitted through OZG-RE, the only federal platform since ZRE was retired in September 2025. States use their own portals. E-invoicing solution providers can connect to these portals automatically.
E-Invoicing Framework (Model) in Germany
Germany's e-invoicing framework follows the Peppol 4-corner model, enabling secure, structured, and interoperable electronic exchange, with enough flexibility to support the Digital Reporting Requirements (DRR) under ViDA when they come into effect.
- Decentralized Exchange (Peppol 4 Corner Model): It does not use a central clearance portal for B2B invoices. Unlike some countries, businesses in Germany do not need to send every B2B invoice to the government platform first before issuing it. Companies can send invoices directly using email, EDI, Peppol, ERP connections, or service provider networks.
- Public Sector (B2G) Portals: For B2G invoices, official portals are still used. Suppliers invoice federal authorities through OZG-RE, the only federal receiving platform since September 2025, and state authorities through state portals. These portals accept XRechnung, and the federal platform can also be reached through Peppol.
- Post-Audit Model: Germany uses a post-audit model. Tax authorities may request invoices during an audit but do not receive them in real time. In July 2026, the federal government announced plans for a VAT reporting system, so this model may evolve.
E-Invoicing Format in Germany
EN 16931-compliant formats like XRechnung and ZUGFeRD are the officially accepted electronic invoice formats in Germany. Both formats defines the mandatory data structure and content required for electronic invoices in Germany.
- XRechnung (XML): Germany’s official EN 16931 implementation, used widely for B2G and accepted for B2B. It’s designed for system-to-system processing, so finance teams typically view it through ERP/accounting tools rather than “reading” the file directly.
- ZUGFeRD (Hybrid PDF/A-3 + Embedded XML): A readable PDF plus structured XML for automation. ZUGFeRD qualifies from version 2.0.1 in every profile except MINIMUM and BASIC-WL, so the BASIC, EN 16931 (formerly COMFORT), EXTENDED and XRECHNUNG profiles are all mandate-ready. If the PDF and the XML differ, the XML is the legally relevant part.
- EDIFACT / Legacy EDI: Under Section 14(1) sentence 6 UStG, trading partners can agree on another structured format if the invoice data can be correctly and completely extracted into an EN 16931-compliant format. This means formats such as EDIFACT, SAP IDoc, X12, VDA or ODETTE can stay in use from 2028, provided any missing mandatory data is added. Until 31 Dec 2027, EDI invoices that do not meet this test remain allowed with the recipient's consent
- Peppol BIS Billing 3.0 (UBL): A standardized way to exchange structured invoices via the Peppol network. It’s a strong option when you need interoperability across many trading partners, provided the content remains correctly mapped to EN 16931.
- XML (General): “XML” alone is not a compliance indicator. A random XML file is not automatically compliant. It must follow an accepted EN 16931 implementation, such as XRechnung XML, ZUGFeRD embedded XML, or properly mapped UBL.
What's next for XRechnung: KoSIT published a preview of XRechnung 4.0 on 15 Sep 2026, based on the revised EN 16931-1:2026. The new core model adds more than 50 Business Terms, including support for several orders and deliveries in one invoice. The full release is expected in spring 2027, and old and new versions can run in parallel until March 2029, so keep using a released XRechnung 3.0 version in production for now.
Who must comply with Germany's e-Invoicing mandate?
The mandate mainly applies to domestic B2B transactions where both businesses are in Germany:
- All domestic B2B Businesses: For transactions where both the supplier and the recipient are based in Germany.
- Businesses Providing Taxable Supplies under VAT: Any taxable supply of goods or services that fall within the scope of German VAT law (UStG).
- Business-to-Government (B2G) suppliers: Business invoicing to federal and state public administrations.
- Foreign Entities with Local Establishments: Foreign businesses operating in Germany with a "fixed establishment" (e.g., a physical office or warehouse).
- All Businesses, for Receiving: Every business in Germany, including small businesses and businesses that mainly sell to consumers, must be able to receive e-invoices from suppliers.
Who is exempt from e-invoicing in Germany
The following transactions and entities are exempt from issuing e-invoices, although every business must still be able to receive them:
- Small-amount invoices: Invoices with a gross total of €250 or less (Kleinbetragsrechnungen).
- Passenger transport tickets: Tickets that serve as invoices.
- VAT-exempt supplies: Most supplies exempt under Section 4 Nos. 8 to 29 UStG, such as financial, insurance and healthcare services.
- Small businesses (Kleinunternehmer): Businesses under Section 19 UStG with turnover of up to €25,000 in the previous year and €100,000 in the current year are permanently exempt from issuing e-invoices under Section 34a UStDV.
- Foreign businesses without a German establishment: Businesses that are only VAT-registered in Germany, without a fixed establishment, are not subject to the issuing obligation.
- Cross-border transactions: Supplies to or from businesses outside Germany, whether intra-EU or non-EU.
- B2C transactions: Sales to private individuals remain outside the scope. Paper receipts or PDFs can still be used.
What are the Mandatory Data Fields for E-Invoicing in Germany?
Every e-invoice must contain the details required by Section 14(4) UStG. Since the BMF letter of 15 Oct 2026, all of them must sit in the structured XML, not only in the PDF or an attachment. The table maps each field to its EN 16931 Business Term (BT), in line with the KoSIT and FeRD mapping table the BMF recommends.
| Mandatory field under UStG | EN 16931 Business Term |
Supplier's full name and address | BT-27 Seller name, BG-5 Seller postal address |
Recipient's full name and address | BT-44 Buyer name, BG-8 Buyer postal address |
Supplier's tax number or VAT ID | BT-31 Seller VAT identifier or BT-32 Seller tax registration identifier |
Invoice issue date | BT-2 Invoice issue date |
Unique, sequential invoice number | BT-1 Invoice number |
Quantity and description of goods, or type and scope of services | BT-129 Invoiced quantity, BT-130 Unit of measure, BT-153 Item name |
Date of supply or service period | BT-72 Actual delivery date, or BG-14 Invoicing period |
Net amount broken down by VAT rate or exemption | BT-116 VAT category taxable amount |
Agreed price reductions such as discounts or rebates | BT-20 Payment terms, BG-20 Document level allowances |
VAT rate and VAT amount | BT-119 VAT category rate, BT-117 VAT category tax amount |
Exemption or reverse-charge note | BT-118 VAT category code, BT-120 VAT exemption reason text |
XRechnung adds its own required fields, such as BT-10 Buyer reference (the Leitweg-ID for B2G invoices) and the seller's and buyer's electronic addresses (BT-34, BT-49). For a field-by-field guide, see Mandatory Data Fields for E-Invoicing in Germany.
E-Invoice Archiving and Retention under GoBD Standards in Germany
Germany requires e-invoices to be archived under GoBD rules in their original electronic format.
- Keep the Original File: XML must remain XML. ZUGFeRD must remain the hybrid file (PDF/A-3 with embedded XML).
- Maintain Integrity and Authenticity: No silent edits. Any corrections must be traceable and logged.
- Apply the Hybrid Invoice Rule: If the PDF and XML differ, the XML is the legally relevant record. The PDF is only a visual rendering.
- Ensure Audit Readiness: Invoices must remain readable, searchable, and exportable during audits.
- Retention period: Invoice retention in Germany is generally 8 years . However, invoices may need to be kept longer if they remain relevant for taxes for which the assessment period is still open; the BMF expressly mentions section 15a UStG real-estate input-tax adjustment cases.
Retention is generally 8 years, but certain cases still require 10 years depending on tax obligations.
E-Invoicing Penalties in Germany
Germany has no separate penalty regime for e-invoicing. The BMF letter of 15 Oct 2026 confirms that issuing a paper or PDF invoice where an e-invoice is required is not an administrative offence under Section 26a(2) No. 1 UStG. The real risks sit elsewhere:
- Input VAT risk for your customer: An invoice in the wrong form does not meet Section 14 UStG, so your customer may not be able to deduct input VAT until you issue a compliant e-invoice.
- Reissue and correction: Non-compliant invoices must be corrected, and the correction itself must be an e-invoice.
- Rejected invoices and late payments: Customers' AP systems may reject invoices that fail validation or lack required references, which delays payment.
- Other VAT breaches still apply: General fines under Section 26a UStG still cover other breaches, such as not issuing an invoice at all or not keeping invoices for the required period.
What Must Businesses Do in 2026?
Here is how German Businesses can be compliant with e-Invoicing obligations:
- Map Current Invoice Flows: Track how invoices are generated, approved, sent, collected, and archived. Also identify places where excessive human effort or repetitive handling still exists.
- Understand Compliance Requirements: Check which invoice documents must shift into e-invoices, which structures are accepted such as XRechnung or ZUGFeRD, along with the applicable implementation timelines.
- Upgrade IT Infrastructure: ERP platforms or bookkeeping applications must handle valid e-invoice structures properly. Some businesses may need extra tools or better software.
- Select the Right E-Invoicing Provider: Assess capabilities, legal compliance scope, connectivity methods, together with customer assistance across different service vendors. Look for certified Peppol access and automatic format validation.
- Establish Internal Policies: Prepare formal workflows for transmitting, accepting, plus archiving e-invoices. Assign duties, accountability, besides escalation procedures for invoice discrepancies or failures.
- Train Employees and Communicate Externally: Accounting, IT, and operations teams should get proper training. Companies should also notify buyers and vendors regarding their e-invoicing arrangement.
- Test Thoroughly Before Going Live: Run pilot e-invoicing programs with chosen vendors and buyers. This helps check if invoices move properly without errors.
- Monitor Regulatory Changes: E-invoicing obligations may evolve gradually. Organizations should frequently monitor official notices plus vendor communications to remain compliant.
How ClearTax Simplifies Germany's E-Invoicing Compliance?
ClearTax helps you go live with Germany-compliant e-invoicing faster, with fewer manual touchpoints. ClearTax is a VeR recognised provider for businesses navigating the current mandate and preparing ahead for E-Reporting (2028) and ViDA's Digital Reporting Requirements (DRR).
- ERP-Compatible Integrations: Connects with SAP, Oracle, Dynamics, alongside additional systems for automated mapping, validation, together with compliant generation.
- Unified Dashboard: Generate, deliver, monitor, plus archive electronic invoices across numerous structures securely through one dashboard.
- Peppol Connectivity: Supports compliant transmission across Germany and EU public-sector processes.
- Continuous Compliance: Built-in validation, regulatory updates, together with secure long-term archiving.
- Scalable Infrastructure: Multi-entity functionality, strong security controls, plus guided onboarding.
Frequently Asked Questions
About Author
I’m a Senior Content Writer at ClearTax, specializing in e-invoicing, VAT, and Tax compliance. Over the years, I’ve researched and written everything from blog posts to whitepapers and product guides, helping ClearTax expand in Malaysia, KSA, UAE, Singapore, Belgium, France and beyond. My goal is to write the most comprehensive, understandable, readable, and accurate content on any topic that has ever existed on the internet. Outside of writing, I love reading self-help books, creating videos, and playing video games.

Rajan Rauniyar
Senior Content Writer- International


